TOTAL LOSS PAYOUT
Thinking About Filing a Claim But Scared of a Lowball Payout?
Call Us First. We Handle the Insurance Negotiations So You Don’t Get Shorted.
We eliminate the stress of dealing with adjusters. Our team locks in your vehicle’s full actual cash value, fights for every dollar you’re owed, plus we hand you $250 CASH the day you drop off your car.
01 / CLAIM ADVOCACY
The 3-Step Process: How Our Pre-Claim Total Loss Valuation Process Works
Our team takes care of every detail to secure your maximum Actual Cash Value (ACV) payout, eliminating the frustration of dealing with insurance adjusters.
01
Drop Off or Tow Your Vehicle (Pre-Claim Intake)
Bring your vehicle to our lot before the adjuster inspects it. If it’s non-drivable, we handle the tow; if you drive in, we pay your Uber home plus an instant $250 drop-off bonus.
02
We Conduct a Full (ACV) Actual cash value Audit & Fight the Insurance Carrier
Your car stays secure while our certified appraisers audit line-item options, local comps, and recent repairs to challenge lowball carrier valuations and demand full Actual Cash Value.
03
Collect Your Maximum Insurance Settlement Check
Your insurance provider sends the payout check directly to you. We bill all storage and administrative fees directly to the carrier—ensuring zero out-of-pocket costs.
02 / HOW WE WORK FOR YOU
Financial Breakdown: Doing It Yourself vs. Working With Us
Scenario: 2018 Truck with an Actual Cash Value (ACV) of $10,000 and a $5,000 Loan Balance
| Breakdown Step | Option A: Handling Alone | Option B: Total Loss Payout |
| Initial Insurance Offer | $6,000 (Lowball) | $10,000 (Full ACV) |
| TLP Cash Bonus | N/A | +$250 Cash |
| Valet/ Towing | Out-of-Pocket | FREE |
| Lender Loan Payoff | -$5k | -$5k |
| 3rd Party Appraisal Fee | N/A | -$300 Deducted from ACV |
| NET CASH IN YOUR POCKET | $1k | $4,950 TOTAL CASH ($4,700 + $250 Upfront) |
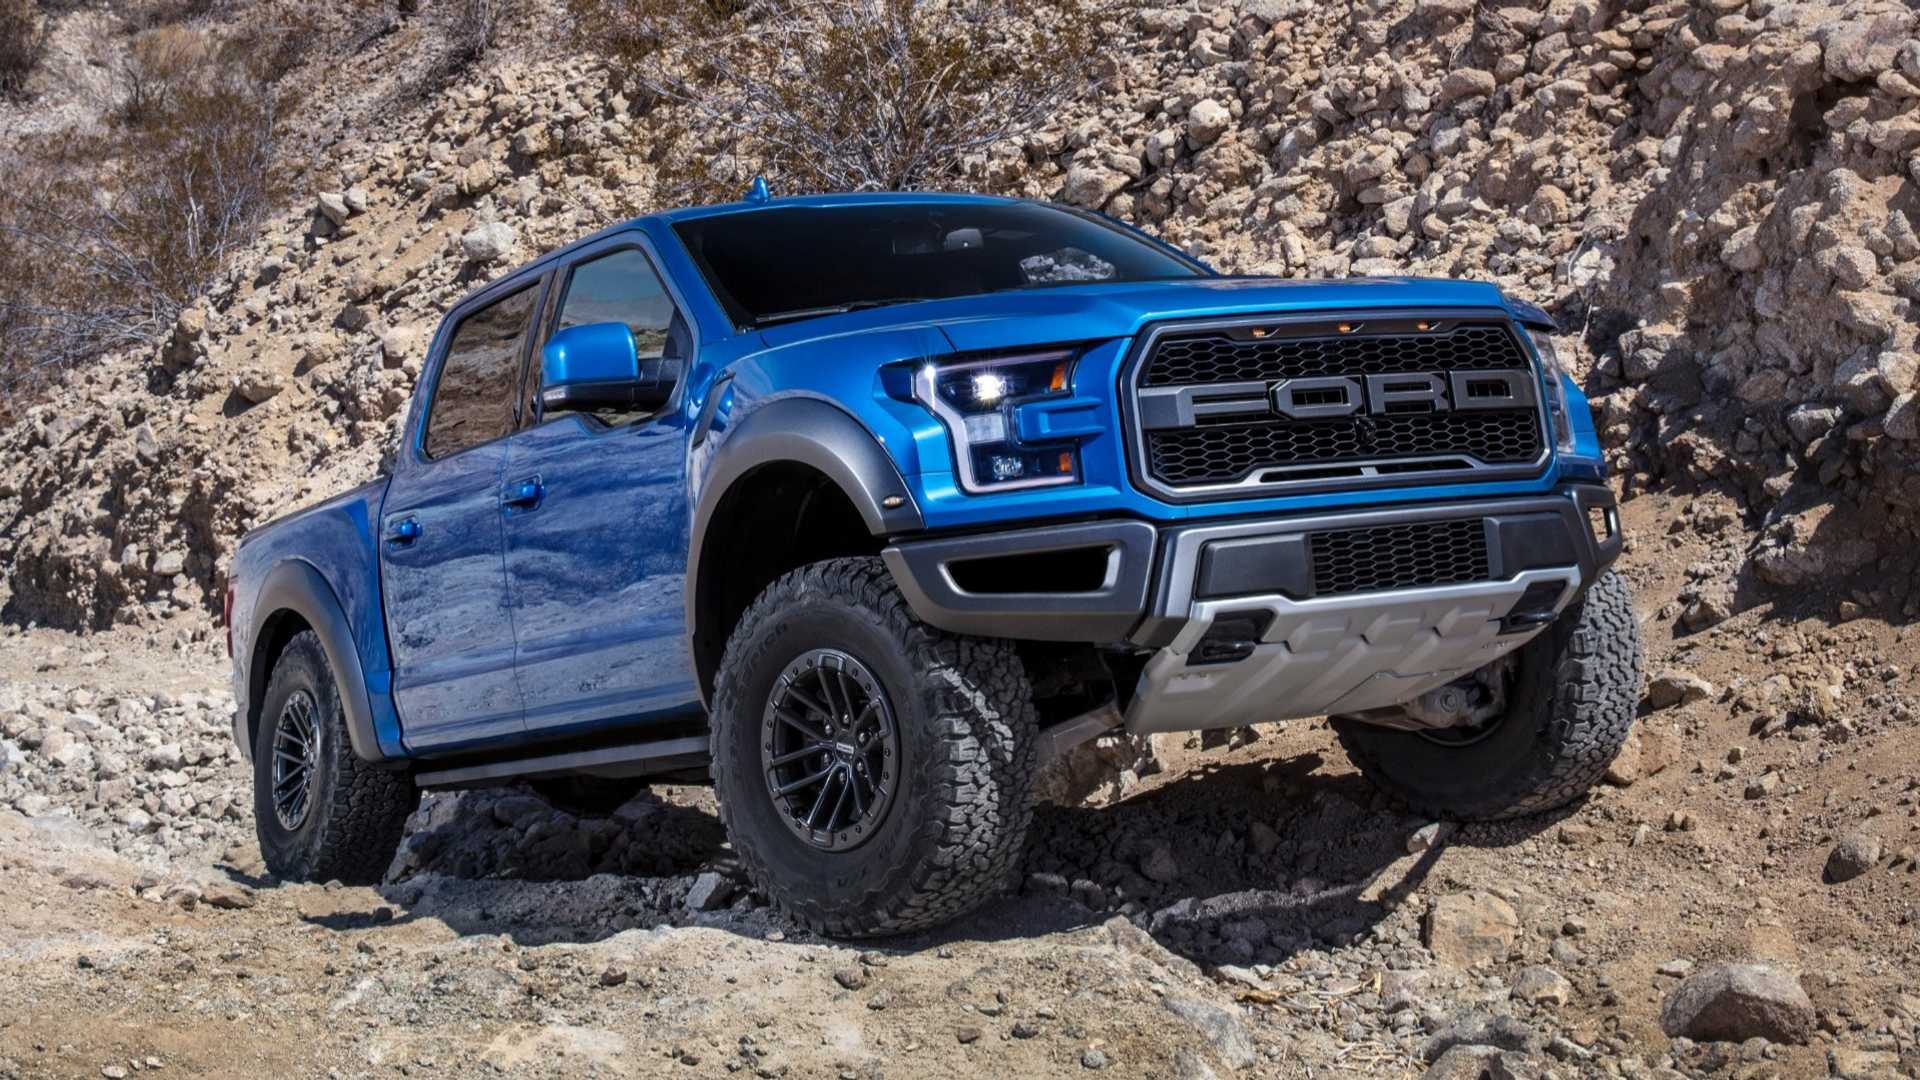
REAL Case Study
2019 Ford F-150 Raptor
Initial Offer: $28,500
(Based on high-mileage 150k-mile automated comps)
Final Audit Settlement: $44,500
(Full ACV locked in after line-item crate engine documentation)
Total Value Added: +$16,250 Net Increase
(+$16,000 Payout Increase + $250 Upfront Cash Bonus)
Total Loss Payout Evaluation
THE POWER OF A COMPLETE AUDIT
The Insurance Trap: Insurance declared the truck a total loss and slapped a massive depreciation penalty on it simply because it had 150,000 miles, making a lowball payout offer.
What They Ignored: The owner had recently installed a brand-new $20,000 crate motor, which was omitted from their automated valuation report.
The Result: We audited the build, gathered the crate engine installation documentation, and forced the insurer to adjust their evaluation line-by-line—recovering thousands of dollars in added payout for the owner.
“When a brutal hailstorm destroyed my Raptor, I knew the insurance company was going to try to total her out with a lowball payout. I’d heard all the nightmare stories about adjusters and wanted expert backing before I even filed my claim. Total Loss Payout stepped in from day one, documented the real value, and made sure I was compensated for the crate motor I had just gotten dropped in. Game changer.”
STILL HAVE QUESTIONS?
TOTAL LOSS PAYOUT FAQS
Have questions about how we handle your claim? Get clear answers on how we take care of total loss disputes, state title laws, storage fees, rentals, and appraisal costs—and how we pay your $250 drop-off bonus.
We are an official vehicle storage and administration facility. Once your vehicle is signed into our lot under contract, we bill the insurance company directly for standard storage fees ($100/day), administrative processing ($250), and vehicle handling ($450). Insurance covers these property storage costs—they are never deducted from your payout.
IThat is exactly why we give you $250 cash the moment you drop your car off (or when we tow it in). You can use that $250 immediately for a rental car, Uber rides, public transit, or gas for a secondary family car. If you need a rental, you can choose to pay the rental company upfront to unlock a ~35% discount, or pay when you return the vehicle after receiving your insurance payout check.
The insurance carrier is legally responsible for rental coverage up until the point a formal “Right of Appraisal” process is invoked. After that point, client rental responsibility begins, which is why our $250 upfront cash buffer helps bridge any gap while your final payout is finalized (typically 1 to 2 weeks once the vehicle is on our lot).
If the insurance company refuses to negotiate reasonably, you have the legal right under your policy to invoke a “Right of Appraisal.” This requires hiring a certified 3rd-party independent appraiser ($300 fee) who works exclusively for you to establish true market value. You do not need cash upfront—we cover the $300 fee for you, and it is simply reimbursed from the much higher final ACV settlement check you receive.
es. Your vehicle remains safely secured at our facility from the day you sign the contract until final settlement funds are issued (usually 1 to 2 weeks).
NO SALVAGE TITLE ON HAIL CLAIMS
Under applicable state guidelines, qualifying vehicles bypass mandatory salvage branding so you retain a clean title.
20+ YEARS OF EXPERIENCE
Your vehicle is a major financial asset. Do not settle for a lowball offer—we make sure you get every dollar it’s actually worth.
VALET & TOWING AVAILABLE
Free valet pickup within the local area. Towing available for inoperable vehicles or broken windshield liability.
ZERO COST CONSULTING
Comprehensive claims review and expert valuation consulting with zero upfront cost.
HAIl OR COLLISION
Specialized advocacy and appraisal reports for both severe hail damage and collision losses.
FREE RIDE ON US
Complimentary valet transport arranged while your vehicle is being appraised or serviced.
03 / Negotiation & Settlement
Already Filed and Received an Estimate or Total Loss Evaluation?
If an adjuster has already inspected your vehicle or declared it a total loss, our upfront drop-off bonus does not apply since the car cannot be stored on our lot prior to inspection.
Reach out to our team with your claim details and official insurance valuation report to discuss your case.
01
Evaluation of vehicle REVIEW
Upload your insurance valuation report. We perform a complete line-item audit to check for missing options, wrong comps, and uncounted upgrades.
02
BACK-END APPRAISAL DISPUTE
If we determine the insurer shorted you, our appraisal team steps in to challenge their “Evaluation of Vehicle” report and demand a proper settlement adjustment.
03
RECOVER YOUR ADDED PAYOUT
We force the insurance carrier to update their valuation line-by-line, securing additional settlement funds directly for you on the back end.